
Vietnam Mobile Game Market Report 2024
Gamota's 2024 report finds the Vietnam mobile game market generated over USD 800 million in revenue, rising 2% year-on-year even as total downloads declined 10% to over 1.6 billion (ninth globally). Vietnamese publishers captured USD 292 million across more than 130 million downloads and launched 127 new titles amid rapid shifts toward Roguelike and Idle RPG sub-genres.
An executive analysis of Vietnam's USD 800M+ mobile game market, domestic publisher performance, sub-genre shifts, and 2024 product design trends from Gamota.
Key findings
- USD 800M+Total Vietnam mobile game market revenue in 2024 (up 2% year-on-year), encompassing both licensed and cross-border unlicensed titles across IAP storefronts and local payment channels (Gamota R&D).
- 1.6B+ downloadsTotal mobile game downloads in Vietnam during 2024 (down 10% year-on-year), placing Vietnam 9th worldwide by mobile game download volume, one spot lower than in 2023 (Gamota R&D).
- USD 292MTotal revenue generated by Vietnamese mobile game publishers in 2024 (up 0.3% year-on-year) across 130M+ downloads (-15%), representing roughly 36.5% of total domestic market spending.
- 127 new gamesNumber of new mobile games released by Vietnamese publishers in 2024 (+25 titles YoY), generating 40M+ downloads (+12%) while new-release revenue declined 22% to USD 70M+.
- +91% & +66%Year-on-year download growth of Vietnam's two fastest-expanding sub-genres in 2024—Roguelike (+91%) and Idle RPG (+66%)—contrasting sharply with contractions in MMORPG (-42%) and Simulation Sports (-48%).
- USD 187.7BGlobal video games market revenue in 2024 (up 2.1% across 3,422 million players), led by mobile gaming at USD 92.6 billion or 49% of worldwide consumer spending (Newzoo).
- 49% of studio staffShare of surveyed global game industry professionals reporting active Generative AI usage at work (31% personally using, 18% used by colleagues) across 3,000 respondents in GDC's 2024 survey.
How did the Vietnam mobile game market grow revenue in 2024 while downloads fell 10%?
In 2024, the Vietnam mobile game market generated over USD 800 million in total consumer revenue, rising 2% year-on-year. Over the same period, total downloads dropped 10% to more than 1.6 billion, moving Vietnam down one position to ninth worldwide in download volume. Gamota's Research & Development team compiled these figures across both locally licensed releases and unlicensed cross-border titles.
Falling install counts alongside steady revenue growth do not indicate weakening player demand. Instead, this divergence marks a structural transition toward market maturity across Vietnam's mobile audience. Players install fewer experimental apps each month while concentrating spending inside established live-service titles with active local communities.
Structural gap between total market volume and domestic Vietnamese publishers
Executives evaluating market entry often conflate total consumer spending in Vietnam with the revenue captured by domestic publishing houses. Separating local publishers from cross-border self-published apps reveals a sharp asymmetry between download share and monetization efficiency:
| Vietnam Market Segment (Full-Year 2024) | Total Downloads | YoY Download Change | Total Revenue | YoY Revenue Change |
|---|---|---|---|---|
| Overall Vietnam market (licensed + unlicensed) | 1.6B+ | -10% | USD 800M+ | +2% |
| Domestic Vietnamese publishers | 130M+ | -15% | USD 292M | +0.3% |
| 127 new titles launched by Vietnamese publishers | 40M+ | +12% | USD 70M+ | -22% |
Vietnamese publishers recorded more than 130 million downloads in 2024, down 15% year-on-year and representing roughly 8.1% of national install volume. Over 90% of raw installs flowed to global casual, puzzle, and hyper-casual titles distributed directly through international app storefronts.
Despite capturing just over 8% of downloads, domestic publishers generated USD 292 million in revenue (+0.3% YoY), or roughly 36.5% of total market spending. Local publishers sustain this monetization premium by operating high-ARPU role-playing and strategy titles, integrating frictionless domestic payment channels, and running localized VIP retention programs.
Which sub-genres gained and lost momentum across Vietnam in 2024?
Across the 130 million-plus downloads managed by domestic publishers, player preferences shifted decisively away from time-intensive grinding toward streamlined session loops. Massively multiplayer online role-playing games (MMORPGs) remained the largest sub-genre by volume at 19% share (24M+ downloads), yet MMORPG installs contracted 42% year-on-year.
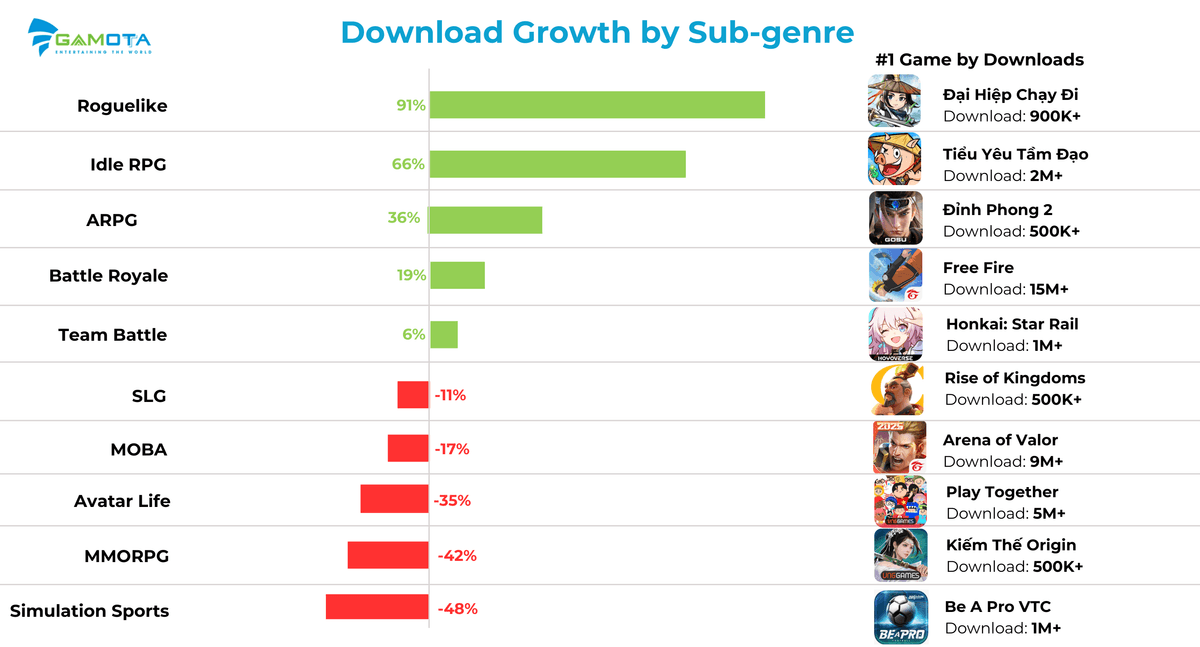
Gamota's sub-genre breakdown highlights a clear bifurcation between bite-sized progression mechanics and legacy core formats:
| Sub-genre in Vietnam (2024) | 2024 Downloads | Domestic Publisher Share | YoY Download Growth | Top Title by 2024 Downloads |
|---|---|---|---|---|
| MMORPG | 24M+ | 19% | -42% | Kiếm Thế Origin (500K+) |
| Battle Royale | 19M+ | 15% | +19% | Free Fire (15M+) |
| Team Battle (Card/Squad RPG) | 15M+ | 12% | +6% | Honkai: Star Rail (1M+) |
| MOBA | 13M+ | 11% | -17% | Arena of Valor / Liên Quân Mobile (9M+) |
| Idle RPG | 10M+ | 8% | +66% | Tiểu Yêu Tầm Đạo (2M+) |
| SLG (4X Strategy) | 5M+ | ~4%* | -11% | Rise of Kingdoms (500K+) |
| Avatar Life | 5M+ | 4% | -35% | Play Together (5M+) |
| Sandbox | 4M+ | 3% | New sub-genre | Roblox VNG (official 2024 launch) |
| Roguelike | Outside top 8 share | Outside top 8 | +91% | Đại Hiệp Chạy Đi (900K+) |
| ARPG (Action RPG) | Outside top 8 share | Outside top 8 | +36% | Đỉnh Phong 2 (500K+) |
| Simulation Sports | Outside top 8 share | Outside top 8 | -48% | Be A Pro VTC (1M+) |
*Data hygiene note: On slide 31 of the source PDF, the SLG callout (5M+ downloads) inadvertently repeats the "8% of all Download" label from Idle RPG; relative to 130M+ total downloads and its pie slice geometry, SLG represents approximately 4%.
Three behavioral shifts reshaping Vietnamese player acquisition
Product and user-acquisition teams can draw three operational lessons from Vietnam's 2024 sub-genre performance:
- Shorter sessions with faster dopamine loops are winning working-age players. Roguelike downloads surged 91% (led by Đại Hiệp Chạy Đi at 900K+ installs) while Idle RPG climbed 66% (led by Tiểu Yêu Tầm Đạo at 2M+ installs). Portrait-mode controls and automated progression let commuters play in three-minute bursts without falling behind guild peers.
- Incumbent competitive franchises monopolize category traffic. Within Battle Royale (+19%) and MOBA (-17%), Free Fire (15M+ downloads) and Arena of Valor (9M+ downloads) absorbed the vast majority of category installs, leaving minimal room for direct clones.
- Licensed Sandbox platforms unlocked a new UGC category. Sandbox debuted as a standalone sub-genre at 3% share (4M+ downloads) following VNG's official domestic release of Roblox in 2024, formalizing user-generated content ecosystems for younger Vietnamese audiences.
Why did 127 new mobile game releases in Vietnam see revenue drop 22%?
Vietnamese publishers launched 127 new mobile titles in 2024, adding 25 more releases than in 2023. Those new releases attracted over 40 million downloads (+12% YoY), yet combined new-title revenue fell 22% year-on-year to just over USD 70 million.
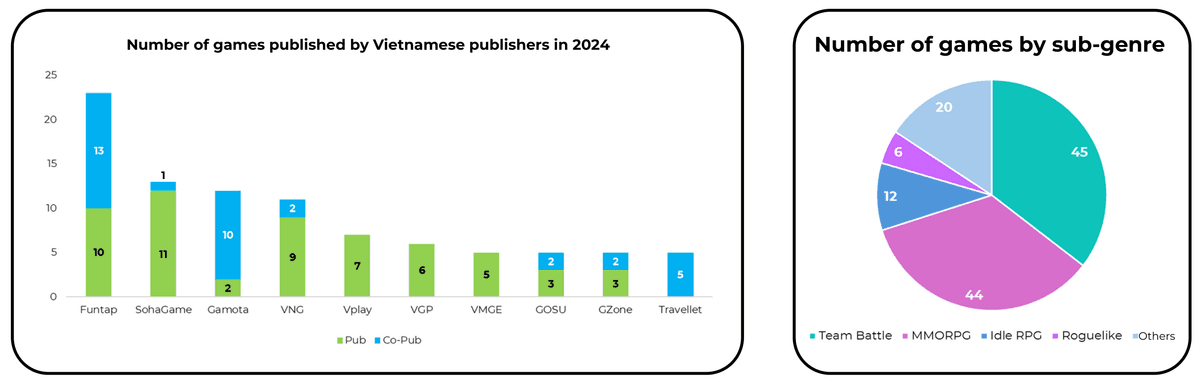
Severe genre crowding explains why expanding release volume failed to lift revenue. Out of 127 new launches, 45 titles belonged to Team Battle (35.4%) and 44 belonged to MMORPG (34.6%). Nearly 70.1% of all new supply competed inside two categories experiencing either modest install growth (+6%) or steep contraction (-42%).
By contrast, Vietnam's two fastest-growing sub-genres—Idle RPG and Roguelike—accounted for only 12 launches (9.4%) and 6 launches (4.7%) respectively, alongside 20 titles across all other genres (15.7%). Launching dozens of overlapping Wuxia and Three Kingdoms titles drove up cost-per-install (CPI) bids while cannibalizing early-cohort spending.
Publishing versus co-publishing models across Vietnam's top 10 publishers
Splitting 2024 releases between standalone publishing (Pub) and co-publishing (Co-Pub) reveals how domestic leaders balanced portfolio volume against licensing and UA risk:
| Vietnamese Publisher | Standalone (Pub) | Co-Published (Co-Pub) | Total 2024 New Games | Primary Portfolio Strategy |
|---|---|---|---|---|
| Funtap | 10 | 13 | 23 | Highest release volume, balancing in-house operations with co-publishing |
| SohaGame | 11 | 1 | 12 | Focused primarily on self-published card battlers and RPGs |
| Gamota | 2 | 10 | 12 | Scaled international partnerships through co-publishing frameworks |
| VNG | 9 | 2 | 11 | Concentrated on flagship IPs, regional blockbusters, and Sandbox |
| Vplay | 7 | 0 | 7 | Operated 100% standalone licensed titles |
| VGP | 6 | 0 | 6 | Targeted core Wuxia and Xianxia RPG audiences |
| VMGE | 5 | 0 | 5 | Standalone publishing across RPG and strategy niches |
| GOSU | 3 | 2 | 5 | Blended self-published ARPG/MMORPGs with co-published releases |
| GZone | 3 | 2 | 5 | Shared launch risk via co-publishing across 40% of new slate |
| Travellet | 0 | 5 | 5 | Specialized exclusively in co-publishing operations |
Co-publishing played a central role for Funtap (13 titles), Gamota (10 titles), and Travellet (5 titles). Through co-publishing, overseas studios pair their product and UA capabilities with a licensed Vietnamese partner's regulatory compliance, local server infrastructure, and domestic payment billing.
Product design lessons from three breakout 2024 launches in Vietnam
Gamota highlights three 2024 releases that outperformed saturated benchmarks by modernizing core progression loops:
- Lục Tung Tam Quốc (Vplay, September 2024, Team Battle + Idle Lootbox). Rather than locking progression behind repetitive stamina stages, this Three Kingdoms squad RPG embedded an idle chest-opening loop and shipped simultaneously across Android, iOS, and lightweight HTML5/H5 (~1 GB footprint).
- Legend of Mushroom / Nấm Lùn Tiến Lên (Sparkgame, March 2024, Idle RPG). Packing nostalgic MapleStory- and Ragnarok-inspired visuals into a 723.99 MB build, the title distilled character growth into an instant lamp-tapping randomized gear loop that retained both casual and mid-core spenders.
- Võ Lâm Đại Minh Tinh (MG.OL, October 2024, Tower Defense + Roguelike). Combining wave-defense mechanics, randomized Roguelike skill drafts, and stylized anime martial-arts heroes (1.5 GB), this hybrid title—alongside Zombie Boom!—led Vietnam's Tower Defense revenue rankings in 2024.
How does the USD 187.7 billion global games market frame Vietnam's trajectory?
Placing domestic numbers beside global benchmarks shows Vietnam is tracking broader international monetization shifts. According to Newzoo's Global Games Market Report 2024 cited by Gamota, worldwide games revenue reached USD 187.7 billion in 2024, up 2.1% year-on-year (recovering from the post-pandemic dip from USD 192.7B in 2021 to USD 182.9B in 2022 and USD 183.9B in 2023, with 2025 forecast at USD 192.6B).
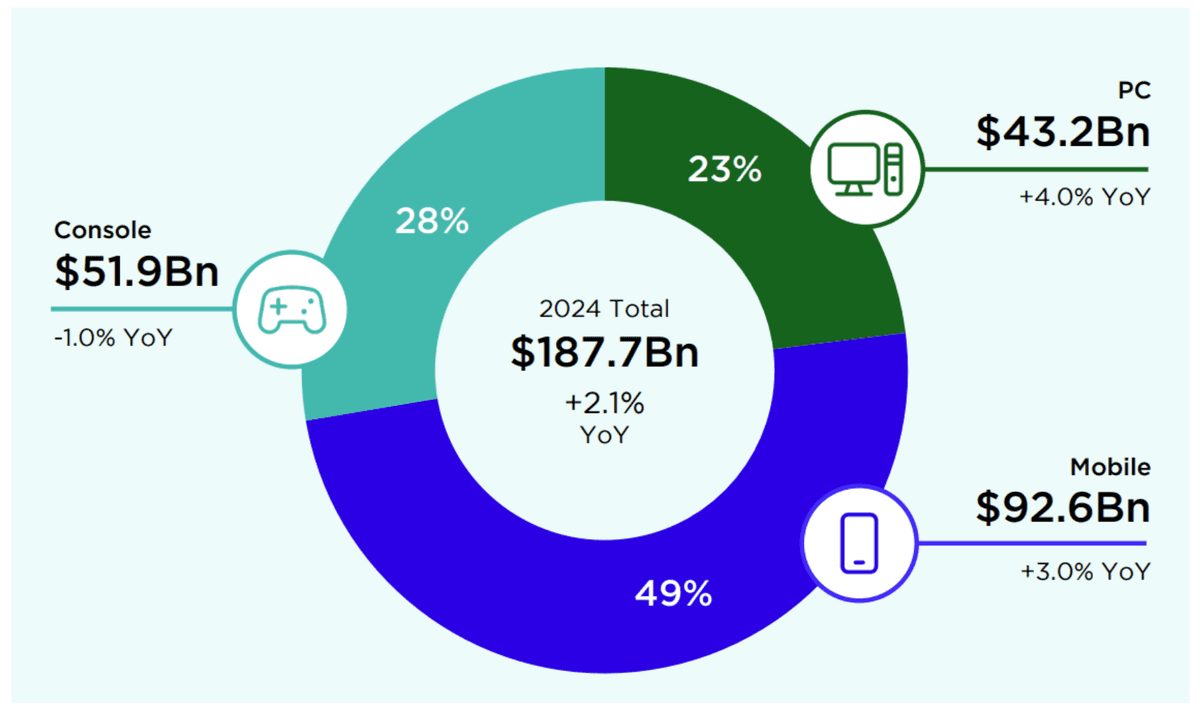
Mobile gaming remained the industry's largest revenue engine at USD 92.6 billion, capturing 49% global share and growing 3.0% year-on-year. PC gaming posted the fastest platform growth at 4.0% to reach USD 43.2 billion (23% share), propelled by cross-platform breakout hits including Black Myth: Wukong, Palworld, and Marvel Rivals. Console spending dipped 1.0% to USD 51.9 billion (28% share) amid a lighter slate of first-party exclusives.
Global player counts rose 4.5% in 2024 to 3,422 million—roughly 42% of the world's population. Asia-Pacific (APAC) anchored global reach with 1,809 million players (53% share, +4.0% YoY), ahead of the Middle East & Africa (559M, +8.2%), Europe (454M, +2.4%), Latin America (355M, +5.6%), and North America (244M, +2.9%). Across device tiers, global mobile players reached 2.85 billion in 2024 and are projected by Newzoo to reach 3.16 billion by 2027.
Sensor Tower global IAP benchmarks and publisher concentration
Narrowing the lens to App Store and Google Play In-App Purchases (IAP) in Sensor Tower's State of Mobile 2025 mirrors Vietnam's exact volume-to-value pivot. Global mobile game downloads declined 6% to 49.6 billion in 2024, while global IAP spending climbed 4% to USD 80.9 billion:
| Global Mobile Genre (Sensor Tower, 2024) | 2024 Global Downloads | YoY Download Change | 2024 Global IAP Revenue | YoY IAP Change |
|---|---|---|---|---|
| Strategy | 2.1B (4% share) | +14.5% | USD 17.5B (21.4%) | +16.2% |
| RPG | ~3% download share | -6.1% | USD 16.8B (20.5%) | -17.3% |
| Puzzle | 9.7B (20% share) | -3.0% | USD 12.2B (14.9%) | +14.0% |
| Casino | ~2% download share | -39.6% | USD 11.7B (14.3%) | +8.9% |
| Simulation | 9.8B (20% share) | +0.4% | USD 6.1B (7.4%) | +8.8% |
| Shooter | 2.4B (5% share) | +1.5% | USD 4.3B (5.3%) | +3.4% |
| Action | 2.4B (5% share) | -7.9% | USD 3.6B (4.4%) | +46.0% |
Sensor Tower's genre table underscores a critical warning for Asian RPG publishers: global RPG IAP spending contracted 17.3% in 2024 to USD 16.8 billion, ceding the top monetization rank to Strategy (USD 17.5B, +16.2% YoY). Meanwhile, Puzzle (USD 12.2B, +14.0%) and Action (USD 3.6B, +46.0%) expanded monetization through deeper meta-progression and LiveOps events.
In AppMagic's 2024 global ranking of top mobile game publishers by net IAP revenue (compiled by Anton Slashcev), Tencent led by a wide margin at USD 6.3 billion (358M downloads). Rounding out the top ten were Scopely (USD 2.0B; 174M downloads), Playrix (USD 1.7B; 216M), NetEase (USD 1.7B; 193M), Dream Games (USD 1.5B; 122M), King (USD 1.5B; 171M), Supercell (USD 1.4B; 239M), miHoYo (USD 1.3B; 82M), FirstFun (USD 1.2B; 102M), and Roblox Corporation (USD 1.2B; 279M).
Case studies of Farlight Games' AFK Journey (6.55 GB) and Infold Games' Love and Deepspace (12 GB) illustrate how top grossing titles justify larger client sizes. AFK Journey evolved 2D idle squad mechanics into a 3D open-world social RPG, while Love and Deepspace fused 3D ARPG combat with daily companion routines (study/workout timers, anniversary reminders, and wellness tracking) to unlock high-LTV female audiences.
Four product trends and an execution roadmap for studios and publishers in Vietnam
Section III of Gamota's report identifies four technology and product-design shifts reshaping studio pipelines entering 2025.
Generative AI adoption moves from marketing automation into asset pipelines
Statista figures cited in the report place the global Artificial Intelligence market at USD 184.05 billion in 2024 (+35.38% YoY), with Generative AI accounting for USD 36.06 billion (19.5% share, projected to grow at a 32.2% CAGR from 2025 to 2030 to reach USD 356.1B). Across gaming studios, GDC's 2024 State of the Game Industry survey of 3,000 professionals found 49% already see GenAI used in their workplace (31% personally using tools, 18% used by colleagues), plus another 15% expressing interest.
Departmental adoption currently skews toward Business & Finance (44%), Community/Marketing/PR (41%), and Production & Team Management (33%), ahead of Programming/Engineering (25%), Game Design (21%), Visual Arts (16%), Audio (14%), Narrative/Writing (13%), and Quality Assurance (6%). Studios increasingly combine visual generators (Flux AI, Stable Diffusion, Kling AI, Luma AI) and speech translation models (SeamlessM4T across 101 languages) to compress production cycles—exemplified by A3Games' simulation title Top Girl (678 MB), where 90% of visual assets were produced with GenAI.
Steam-to-mobile fast-follows, UI/UX templatization, and genre hybridization
Alongside GenAI workflows, Deconstructor of Fun and Gamota R&D highlight three product strategies lowering commercial launch risk:
- Fast-following breakout PC simulation hits onto mobile. After Supermarket Simulator went viral on Steam in 2024, mobile adaptations accumulated over 38 million combined downloads. Speed to market and 3D UX polish separated winners from late clones: My Supermarket Simulator 3D (launched July 19, 2024) and Supermarket Simulator Games 3D (August 29, 2024) each surpassed 1 million downloads with USD 10K+ to USD 100K+ in IAP revenue, whereas late entrant Supermarket Simulator City 3D (October 8, 2024) stalled at 200K+ downloads and USD 1K+ revenue.
- Reusing proven UI/UX frameworks (Game Templatization). Studios cut months of onboarding iteration by adapting validated portrait-mode progression shells—such as Capybara GO! building upon Legend of Mushroom's interface clarity, or HoYoverse extending core ARPG combat systems across open-world and turn-based releases.
- Blending two to three sub-genres (Multi-Genre Hybridization). Pairing low-CPI casual or Roguelike front-end mechanics with deep mid-core RPG or strategy monetization widens top-of-funnel reach without sacrificing late-game payer depth.
Four-step action plan for game studios and publishers entering Vietnam
Translating Gamota's 2024 dataset into execution requires four disciplined priorities:
- Rebalance licensing slates away from un-differentiated MMORPGs and squad battlers. Before greenlighting new prototypes or minimum guarantees, portfolio committees should prioritize underserved growth mechanics—Idle RPG, Roguelike hybrids, Tower Defense hybrids, and 3D simulation—over the two legacy sub-genres absorbing 70.1% of new releases.
- Build G1–G4 licensing lead times and co-publishing structures into launch schedules. With Decree 147/2024/ND-CP taking effect in late December 2024—mandating local corporate presence, Vietnamese mobile-number player verification, and under-18 playtime safeguards—international and domestic teams should map milestones using our six-stage guide to mobile game publishing in Vietnam.
- Gate user-acquisition scaling behind cohort retention and Net LTV validation. With average revenue across new 2024 launches down 22%, publishers should avoid front-loaded launch spend and test stability, retention, and payback sequentially via our three-gate mobile game soft-launch checklist.
- Harden local payment gateway integrations and automated settlement checks. Domestic publishers capture 36.5% of market revenue on 8.1% of downloads largely by offering seamless e-wallet, QR, and local bank billing alongside app store IAP. Engineering teams must enforce cryptographic IPN verification and idempotent item delivery using our payment gateway integration checklist for mobile apps, and track ongoing market benchmarks in our gaming business and publishing hub.
This web report distills the verified market metrics and strategic takeaways from Gamota's annual study. Complete the download form on this page to access the full 55-page PDF compiled by Gamota, featuring full game-by-game teardown cards, global seasonality curves, and the complete GenAI production tooling map.
Sources
- Báo cáo thị trường game mobile Việt Nam 2024 (2024 Mobile Game Market Report), Công ty Cổ phần Gamota (Team Research & Development), 2025-02-19, accessed 2026-10-30
- Global Games Market Report 2024, Newzoo, 2024-08-06, accessed 2026-10-30
- State of Mobile 2025, Sensor Tower, 2025-01-16, accessed 2026-10-30
- Top Mobile Game Publishers of 2024 by Net IAP Revenue and Downloads, AppMagic (Anton Slashcev tổng hợp), 2025-01-10, accessed 2026-10-30
- Artificial Intelligence & Generative AI — Worldwide Market Forecast 2024–2030, Statista, 2024-06-01, accessed 2026-10-30
- 2024 State of the Game Industry, Game Developers Conference (GDC), 2024-01-18, accessed 2026-10-30
- Meta x Kwalee: Leveling Up Mobile Gaming with Hybrid Monetization and AI, Deconstructor of Fun, 2024-11-19, accessed 2026-10-30
- Nghị định 147/2024/NĐ-CP về quản lý, cung cấp, sử dụng dịch vụ Internet và thông tin trên mạng, Chính phủ nước Cộng hòa xã hội chủ nghĩa Việt Nam, 2024-11-09, accessed 2026-10-30
